Ukaguzi Sacco Reports Ksh47 Million in Loan Defaults as Ksh50 Million KUSCCO Investment Faces Uncertainty
Ukaguzi Sacco is facing increased scrutiny over loan repayment challenges and an investment of Ksh50 million in the Kenya Union of Savings and Credit Co-operatives (KUSCCO), according to a report published on October 16, 2026. The latest findings highlight financial risks facing the Sacco even as its lending portfolio and operating income continue to grow.
The developments raise important questions about loan recovery, investment management and the protection of members’ savings.
Ksh47 million in loans remain unpaid
According to the Sacco’s Supervisory Committee report presented during its 53rd Annual General Meeting on March 28, 2026, Ukaguzi Sacco recorded Ksh47.03 million in loan defaults as of December 31, 2025.
The committee broke down the outstanding loans into three categories based on the duration of non-payment and the level of risk.
Ksh3.27 million was classified as losses after remaining unpaid for more than one year. Another Ksh13.95 million was classified as doubtful or substandard, with repayments overdue by between 91 and 360 days. The remaining Ksh29.81 million was overdue by between 31 and 90 days.
The committee expressed concern about the performance of Ukash loans, identifying high default rates as an area requiring urgent attention. It recommended stricter borrower screening, improved credit scoring and tighter eligibility requirements to reduce the risk of lending to members who may struggle to repay.
These measures are intended to strengthen credit management and limit potential losses arising from unpaid loans.
Ksh50 million investment in KUSCCO raises concerns
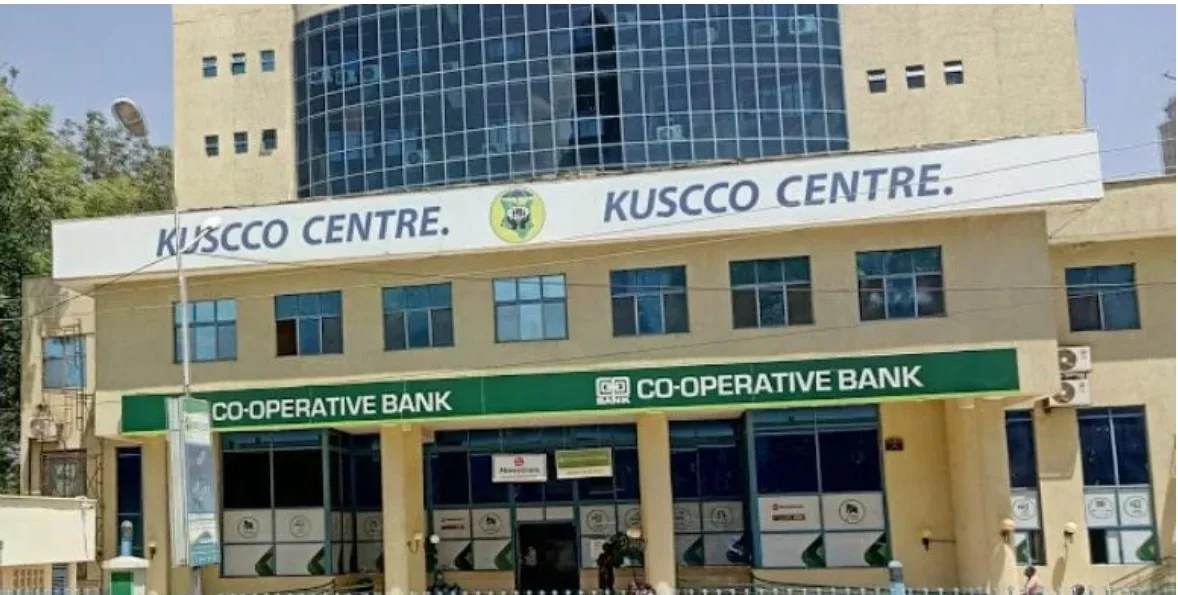
Another major issue highlighted in the report is Ukaguzi Sacco’s Ksh50 million investment in KUSCCO, made in 2023.
According to the latest report, the Sacco received only Ksh756,705 in 2025 in connection with the investment, equivalent to 1.43 per cent of the expected amount reported by the committee. The Sacco’s board was continuing discussions with KUSCCO management regarding the outstanding balance.
The uncertainty surrounding the investment comes amid wider financial difficulties at KUSCCO, the umbrella organisation serving savings and credit cooperatives in Kenya.
In a related development, Business Daily reported in August 2026 that KUSCCO members had voted to place the organisation into voluntary liquidation. The report indicated that Saccos owed approximately Ksh17 billion could recover only Ksh5.4 billion from known assets, leaving a substantial potential shortfall.
For Ukaguzi Sacco, the situation creates uncertainty over how much of its original investment it may eventually recover. However, the final amount recoverable by the Sacco has not been established in the reports reviewed.
Loan portfolio grows despite repayment challenges
Despite the reported defaults, Ukaguzi Sacco’s lending business continued to expand in 2025.
The Sacco’s loan portfolio grew by 6.68 per cent to Ksh3.02 billion, while loans disbursed during the year increased slightly to Ksh1.69 billion, compared with Ksh1.68 billion in 2024.
The growth demonstrates continued lending activity, but it also highlights the importance of ensuring that borrowers can meet their repayment obligations.
Stronger loan assessment procedures and effective debt recovery could help the Sacco manage the risks associated with expanding its lending portfolio.
Ksh98.85 million in unremitted member contributions
The Supervisory Committee also raised concerns about Ksh98.85 million in member contributions that employers had deducted but had not remitted to the Sacco by December 31, 2025.
Delayed remittances can complicate the management of members’ accounts and create challenges in reconciling contributions with the amounts received by the Sacco.
The issue highlights the importance of strengthening follow-up procedures with employers and ensuring that deductions made on behalf of members are transferred promptly.
Operating income rises as expenditure exceeds budget
Ukaguzi Sacco recorded operating income of Ksh510.90 million in 2025, exceeding its budget of Ksh388.45 million by approximately 31.5 per cent.
However, expenditure also exceeded the budget. The Sacco reported expenditure of Ksh398.36 million against a planned Ksh375.37 million.
Although the higher operating income indicates stronger income generation than anticipated, the expenditure figures underline the need for effective cost control and financial planning.
The Supervisory Committee recommended stronger risk management, improved oversight and a review of potential tax obligations, including possible excise duty and withholding tax liabilities.
These issues will be important considerations as the Sacco works to protect its financial position and maintain members’ confidence.
Membership increases to 2,455
Ukaguzi Sacco’s membership rose from 2,376 in 2024 to 2,455 in 2025, representing an increase of 79 members.
Membership growth provides an opportunity for the Sacco to expand its savings and lending services. Sustaining that growth, however, will depend partly on effective governance, responsible lending and the timely collection of outstanding debts.
For members, the latest findings underscore the importance of following the Sacco’s official financial disclosures and AGM communications when assessing its performance.
What the latest developments mean for Ukaguzi Sacco members
The latest report presents a mixed picture of the Sacco’s performance. Operating income and the loan portfolio increased, and membership continued to grow. At the same time, loan defaults, delayed employer remittances and uncertainty surrounding the KUSCCO investment remain important concerns.
The committee’s recommendations point to several priorities for the Sacco’s leadership:
-
Strengthen borrower assessment and loan approval procedures.
-
Improve the recovery of overdue loans, particularly high-default loan products.
-
Continue pursuing clarification and recovery of the KUSCCO investment.
-
Follow up on outstanding employer contributions.
-
Improve expenditure controls, financial oversight and tax compliance.
These steps could help strengthen accountability and reduce financial risks if implemented effectively.
Members should distinguish between the financial concerns identified in the Supervisory Committee’s report and a conclusion about the Sacco’s overall solvency. The figures reported do not, by themselves, establish that Ukaguzi Sacco is insolvent or unable to meet its obligations.